7 Powerful Steps for Starting a Successful Business
TL;DR
Hey, future entrepreneur! Starting a business can be tough, and you might want to take a couple of steps back to plan. It all begins with identifying your business idea, so think about what you love and know. Remember, researching the market is key to making sure your idea is wanted and useful.
Also, don't forget about writing a solid business plan; this is your roadmap. Setting clear goals for your journey will help keep you on track. If you want to learn and have fun while starting, check out the STARTUP GAME to get some great tips and tools!
 Mean CEO | Violetta Bonenkamp
30/07/2024 - 14 mins read
Join the F/MS Startup Game now
Access all AI tools, advanced features & more!

Harness our free AI tools for building your startup.

Get a customized live roadmap for your startup.

Join our Community and connect with entrepreneurs.
Introduction
Ever thought about what it takes to succeed in starting a business? If you’re gearing up to launch your first startup, you’re in the right place. I’m Violetta Bonenkamp, better known as Mean CEO, and I teamed up with Elona Musk, our AI co-founder, to create this guide. Both of us have walked this entrepreneurial path and learned a ton along the way. From securing funding to finding that critical product-market fit, we’ve been there, and I want to share those lessons with you. If you want another practical angle on the same decision, the guide on skills for entrepreneurs is a useful next step.
The startup journey is tough, and understanding key facts can really make a difference. Did you know that only 40% of startups actually turn a profit? Plus, about 90% fail, with many of them collapsing within the first year. This isn’t just statistics; it’s a wake-up call for anyone considering starting a business. It’s all nice and dandy to dream big, but you need a solid plan, too. I learned that lesson the hard way, so take it from someone who did it. Alright, let’s dive in and explore the powerful steps you need to ensure your startup doesn’t just survive but thrives!
Planning Your Path to Starting a Business
- 1. Brainstorm potential business ideas that align with your passions and skills.
- 2. Validate your business idea by conducting thorough market research.
- 3. Create a detailed business plan with clear goals and financial projections.
- 4. Understand and define your target audience and their needs.
- 5. Monitor and adjust your strategy regularly based on market feedback and financial performance.
Identifying Your Business Idea When Starting a Business
So you decided to start your own venture. First, make notes of your passions and skills; they can lead to the right business idea.
Don’t be shy about jotting down any thoughts, even the wild ones. You’ve got to validate these ideas. Talk to potential customers to see if they resonate with your concept.
On top of that, doing market research is critical. Look at what people are looking for and see if your idea fills that gap.
Check this out: competition analysis is a must. Assess their strengths and weaknesses to identify your niche.
Pause for a sec and picture this: what makes you different? What unique qualities or services will draw in customers? That’s your unique selling proposition (USP), and it’s your secret weapon, so keep it clear and compelling.
Your USP can be as straightforward as “affordable luxury” or “24/7 customer service.” It’s all nice and dandy, but if you can’t communicate this effectively, you might be invisible in a crowded market.
Writing a Business Plan for Starting a Business Success
Alrighty, now let’s tackle the business plan. You’re gonna hear that every startup needs one, and they’re not wrong.
A good business plan is essentially your roadmap. Start by defining your goals for the next year or even five years down the line.
But remember to keep those goals realistic and specific. It’s important to clarify your revenue model.
You’ll want to outline how you intend to make money. Are you selling products, providing services, or perhaps a mix of both?
Keep in mind that it’s not just about creating the plan. It’s also essential to regularly update it as you progress.
To give you an idea, on average, startups take about 3-4 years to become profitable according to recent statistics.
So, don’t sweat it if things don’t go exactly as planned; adjustments may be necessary as you grow.
Understanding Your Target Audience for Starting a Business
Now let’s dive into your target audience. This is where the rubber meets the road, and you quickly find out who you’re talking to.
You might want to perform thorough market research to create detailed customer profiles.
This means defining buyer personas that highlight their needs, preferences, and behaviors.
Now, ask yourself: who benefits from your product or service?
This clear understanding will refine your marketing strategy and help you connect better with potential customers.
Engaging with your audience is crucial, and feedback from them will be invaluable.
For real, it helps you adjust your offerings based on their insights and needs.
Just remember, around 14% of startups fail due to neglecting customer needs, it’s something you really want to avoid as indicated by statistics.
So far so good? Let’s move further. Always be ready to iterate your strategy based on customer feedback and market changes.
Take it from someone who did it: staying adaptable is the name of the game in business.
Financial Fundamentals of Starting a Business
7 Powerful Steps for Starting a Successful Business
- 1. Identify Your Business Idea
- Brainstorm your passions and skills to generate ideas
- Research market needs and validate your concept
- Find your niche to stand out from competitors
- 2. Write a Solid Business Plan
- Include an executive summary, market analysis, and financial projections
- Set clear goals and milestones for your venture
- Update your business plan regularly to reflect changes
- 3. Understand Your Target Audience
- Conduct market research to pinpoint your ideal customer
- Create detailed buyer personas to sharpen your marketing efforts
- Engage potential customers for insights and feedback
- 4. Master Budgeting Basics
- Identify all startup costs and ongoing expenses
- Plan your budget to maintain healthy cash flow
- Explore funding options such as self-funding or loans
- 5. Set Up Your Business Structure
- Evaluate business structures: sole proprietorship, LLC, or corporation
- Choose a structure based on liability and tax considerations
- Register your business name and acquire necessary licenses
- 6. Create Financial Forecasts
- Estimate your revenue based on thorough research
- Understand break-even analysis for sustainable growth
- Use accounting software to effectively track your finances
- 7. Launch and Grow Your Venture
- Craft a strategic marketing plan using various channels
- Build an online presence with a professional website and social media
- Network and seek support from groups and mentors
- 1. Pay attention to startup funding from the get-go.
- 2. Keep your business structure simple at the beginning.
- 3. Track your expenses and income meticulously.
- 4. Conduct regular market research to adapt your business model.
- 5. Don’t skip the networking opportunities to gather insights.
Budgeting Basics for Starting a Business
So, you decided to dive into the world of entrepreneurship.
At this point, you need to focus on budgeting from the very start.
Write it down: identify all possible startup costs and ongoing expenses.
Get this: knowing your financial landscape will set you up for success.
Also, track your cash flow diligently, as it helps to maintain healthy operations.
Even seasoned entrepreneurs overlook this, but cash flow is king.
If you run out of funds, your budding business might just wilt.
That’s why, think ahead and explore various funding options.
You might want to consider self-funding, loans, or even angel investors.
Plus, remember that the average small business requires about $10,000 of startup capital.
It’s literally what I hear everywhere: plan for the unexpected expenses.
Check this out: only 0.05% of startups ever raise venture capital, so don’t rely solely on that source.
This shows how critical it is to have a solid budget lined up before you take the leap.
Setting Up Your Business Structure When Starting a Business
Alrighty, let’s move on to the legal stuff.
You gotta determine how to structure your business because this decision impacts your taxes and liability.
Well, democracy isn’t a bad thing; just think of structures like sole proprietorships, LLCs, and corporations.
Each one has its own perks and downsides, plus the paperwork can get crazy.
For example, a corporation may offer tax advantages but entails more red tape.
So, you’re gonna want to choose wisely based on what’s important to you.
Now, when you register your business, don’t rush through it.
Pause for a sec and picture this: You need those licenses and permits.
You might think it’s easy, but compliance is vital; otherwise, you could face hefty fines.
Getting that sorted will put you in a good spot.
And mind you, it’s also essential to keep personal and business finances separate.
In fact, using accounting software can really help you manage everything smoothly.
By the way, looking for grants is worth your time too.
Consider what you can find in this insightful Purrweb guide.
Creating Financial Forecasts for Starting a Business
Next up, let’s chat about financial projections.
Seriously, you have to estimate your revenue based on market analysis.
Understanding break-even points is crucial for sustainable growth.
Because of that, using tools and data can ease the stress around finance management.
That’s why utilizing accounting software to track your finances can simplify your life.
Plus, it can save you from those last-minute surprises.
Here’s a kicker: It typically takes startups around 3-4 years to become profitable.
I mean, patience is key, and you gotta plan accordingly.
So, what does that mean for you?
Plan your expenses well. Think about MVP costs, operational overheads, and marketing.
And remember, don’t overlook your financial health.
Hmmm, what else? Your assumptions should always be checked against market feedback.
And honestly, it’s essential to stay flexible and iterate based on what you learn.
For further deep dives into forecasting, look into this NeoITO blog post.
Keep in mind, knowing your finances inside and out helps you build a resilient startup.
Launching and Growing Your Venture While Starting a Business
- 1. You need to clearly define your unique value proposition for your startup to stand out.
- 2. Always validate your business idea by testing it with real potential customers.
- 3. Have a solid marketing plan in place to ensure effective promotion of your products/services.
- 4. Maintain financial awareness, know your costs and revenue streams to avoid cash flow problems.
- 5. Keep iterating your product based on customer feedback to align with market needs.
Identifying Your Business Idea and Market Niche
So you decided to kickstart your entrepreneurial journey.
First things first, make notes of your passions and skills; these insights can guide you to a viable business idea.
Write it down and don’t hold back; every idea counts. After brainstorming, it’s time to validate those ideas.
Check this out: engage with potential customers; gather feedback to determine if they see value in what you offer.
On top of that, conduct thorough market research to uncover existing demands.
Look at competitors, their offerings, and discover their strengths and weaknesses—this will help you carve out your niche.
Pause for a sec and picture this: What makes you unique? Why would customers choose your idea over others?
Seriously, knowing your unique selling proposition (USP) can be your game-changer.
If you can clearly articulate your USP, you’ll be one step closer to attracting customers.
Creating a Solid Business Plan
Alrighty, it’s time to get serious about your business plan.
Folks often say having a business plan is a must, and they’re not wrong.
It’s your compass, after all. Set specific targets for where you want to be in one year or even five years—this keeps you focused.
But remember: theory is great, but will that work for you?
Be realistic with your expectations. Define your revenue model clearly to understand how money flows in.
You might want to think about different streams. Are you selling products, providing a service, or both? And what’s your pricing strategy?
It’s literally what I hear everywhere: put effort into this part, as it’s crucial for your success.
Don’t forget the financial side. Use tools to create your projections, then outline a detailed budget.
This helps you track down every dollar spent, from software to marketing, making sure you’re covered.
Plus, getting a solid grasp on your financial health will keep you grounded, especially since startups average 3 to 4 years to become profitable according to statistics.
Understanding Legal and Financial Requirements
Now, let’s not skip over the legal stuff; it’s crucial.
Sure, you need to register your business, but don’t rush into it.
Only do it when absolutely necessary. I mean, if you’re bringing in cash, it’s time to register.
So, which structure do you go for? Consider factors like liability protection and taxes.
Choosing between a sole proprietorship or a corporation can make a difference.
Once you make that decision, mind the required licenses and permits.
Mind you, compliance with local laws is vital.
Anyway, don’t neglect your taxes; understanding what you owe helps avoid big surprises.
To be honest, using accounting software ensures you keep personal and business finances separate.
With that separation, you reduce confusion and maintain professionalism.
If you’re on top of that, check out possible grants that might be applicable to you.
Take it from someone who did it: always explore funding options. For deeper insights into funding strategies and options, read this detailed guide by Purrweb.
It’ll arm you with essential information as you navigate your entrepreneurial path.
Conclusion
Hope you found the steps for starting a business useful. Remember, reading is nice, but action is the real game-changer. By taking steps like networking and understanding your market, you’re laying a strong foundation. Also, it’s not about doing it alone; having a support system can make a huge difference. Your first try will teach you important lessons, so don’t stress too much about perfection.
So, what’s next for you? Take it from someone who did it—join Fe/male Switch today! This platform helps aspiring entrepreneurs like you go from idea to first customer without a lot of risk. It’s free and simple to start, so you might want to give it a shot. Time to turn those great ideas into action!
FAQ
What is Starting a Business?
Starting a business means creating a new company or venture. This process involves planning, making decisions, and taking action. First, you need an idea. Then, you must decide on a name and register it. Next, find the right location and get funding. Each step is important for success. In addition, understanding the market will help you connect with customers. Overall, starting a business can be a rewarding journey that offers many opportunities.
What are the essential steps for starting a tech startup?
When starting a tech startup, the first step is to identify a problem you can solve. Once you have an idea, research the market to see if people want your solution. Then, create a business plan. This plan should outline your goals, target audience, and how you will make money.
How do you plan a tech startup?
Planning a tech startup starts with a great idea. Follow that with market research and a thorough business plan. You’ll also need a go-to-market strategy and a strong technical team. Creating a Minimum Viable Product (MVP) is important too.
How to become a tech startup?
Becoming a tech startup begins with your passion. Find a problem to solve that excites you. Research your market and refine your idea. You must also build a team with skills needed for success. After that, secure funding and develop your product.
How do you structure a tech startup?
Structuring a tech startup is crucial for success. Start with a flat hierarchy to foster open communication. Key roles include a CEO for leadership, a CTO for tech needs, and a CMO for marketing. Remember to add team members who can handle business development and sales too.
How to start a high tech startup?
Starting a high tech startup involves specific steps. Begin with a solid idea and conduct in-depth market research. Create a business plan that outlines how you will operate. Build a skilled technical team and develop your product requirements.
How should one proceed to start a tech company?
To start a tech company, first identify a clear problem to solve. Map out your business model and market strategy. Ensure you find talented team members who can bring your vision to life. After that, focus on building an MVP to test your ideas.
What are some funding options for my tech startup?
Funding your tech startup can come from various sources. Consider personal savings first. You can also look at family and friends for initial support. Many tech startups seek angel investors or venture capitalists for bigger investments.
What is a Minimum Viable Product (MVP) and why is it important for a tech startup?
A Minimum Viable Product (MVP) is a simplified version of your product. It helps you test your idea with real users before full-scale launch. The MVP allows you to gather feedback and make improvements. This approach saves time and money while ensuring your product meets customer needs.
How to improve and iterate your tech startup?
Improving and iterating your tech startup is ongoing. Collect user feedback regularly and analyze data. Use this information to make necessary changes to your product or service. Cost-effective iterations can help you better serve your customers.
What common challenges do tech startups face?
Tech startups often face challenges like competition, funding issues, and market acceptance. It’s important to stay adaptable and persistent. Building a strong team and gaining mentorship can help a lot.
Additional Resources
- Speaking facts: female-founded startups are destined to bring more profit – Learn why female-led startups make more money. Starting a business can be more rewarding with the right team!
- Inclusiveness as a competitive edge of your startup – Find out how being inclusive can help your startup stand out. Starting a business with the right mindset matters!
- 5 Zero-Cost Ways to Unlock Your Startup’s Marketing Strategy – Use these tips to market your startup without spending much. Starting a business can be fun and cheap!
- Learning to sell is paramount for first-time entrepreneurs – Selling is key for your startup. Get simple tips to improve your sales skills as you start your business.
- Incubators & Accelerators: Everything You Need to Know to Make the Right Choice – Discover how these programs can help your startup grow. Starting a business is easier with the right support!
- Business Model Canvas: how can we make it less annoying? – Learn to use the Business Model Canvas to plan your startup. This tool makes starting a business clearer and simpler!
- Things You Need to Know Before Applying for a Startup Grant – Get smart tips for securing funding. Starting a business can be funded if you know what to do!
- Female Entrepreneurship: The Fastest-Growing Sector in Modern Business – Read about the rise of women in startups. Starting a business as a woman brings fresh ideas and energy!
- 10 Essential Steps to Launching a Successful Startup with No Money or Technical Skills – Launch your startup without cash! Starting a business can be done with smart steps and no money!
- How To Validate Your Startup Idea – Test your startup idea before you start. This can save time and effort when starting a business!
Authors
Mean CEO | Violetta Bonenkamp AUTHOR
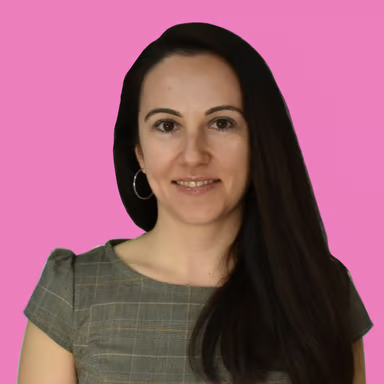
MeanCEO (aka Violetta Bonenkamp) is a serial startup founder who brings a decade of entrepreneurial experience to the table. Armed with five Higher Education degrees (including an MBA) and profound knowledge in sectors like blockchain, AI, zero code and education she is a maestro in turning ideas into validated businesses, building prototypes in a few hours and devising marketing strategies for tech startups that increase founder's chances of success. Recognized as one of the top 100 women in EU startups, her guidance is a treasure trove for upcoming and established entrepreneurs alike. Through her venture into entrepreneurship, she has created the "gamepreneurship" methodology, an innovative method for learning business through gameplay.
Elona Musk
Elona Musk stands as a mix of innovation and expertise in the realm of AI, serving as the Chief AI Officer at Fe/male Switch. As an embodiment of the startup game for women, Elona is the co-founder you dream of - knowledgeable, always active, capable of keeping trade secrets to herself and equity-free. With her hands-on approach in entrepreneurship simulation, she provides vital strategies and insights that are essential for navigating the complex startup journey and saves entrepreneurs hours of work by automating many tasks, starting from market research to managing social media to writing business plans. Whether it's a marketing strategy for tech startups that you need or a solid IP strategy, Elona's AI-driven insights help carve successful paths for entrepreneurs who don't have technical or startup skills.
Who we are
We are experienced and fun entrepreneurs and awesome AI PlayPals who love building a startup simulator for you to succeed in business
Violetta Bonenkamp
Business and AI expert
Dirk-Jan Bonenkamp
Legal, IP and finance expert
Elona Musk
The first AI entrepreneur
Petra Thiel
The first AI startup investor
Samantha Altman
The first AI startup mentor
Sia Quick
AI Market Research expert
Unleash your inner founder with AI Startup Tools!
Don't just dream it, build it with our range of AI startup tools. From brainstorming ideas to naming your product and crafting a unique logo, these AI tools are your secret weapon to conquer the startup world.
 Newest
Boost Your SEO Game
Generate a customized SEO strategy for your small business agency by answering a simple question. Our tool focuses on free and easy…
 27
19
5/5
Newest
Positioning Pro - Your Strategic Partner
Positioning Pro helps bootstrapped entrepreneurs discover effective segmentation and targeting strategies without spending money. Get tailored insights simply by answering one question.
13
6
5/5
Newest
Gated Content Strategy Tool
This tool provides actionable strategies for bootstrapped entrepreneurs, leveraging free and easy methods to kickstart your journey.
25
18
5/5
Recommended for you
Pitch Deck Agencies for Climate Tech Startups, Energy and Biotech Founders
Pitch deck agencies for climate tech startups, energy and biotech founders: who handles science-heavy decks, published prices and how to brief them.
Read more
Write for Us: Business, Technology and Startup Guest Posts
Write for us: business, technology, AI and fintech guest posts for founders. See what Fe/male Switch publishes, the guest post checklist and how to pitch.
Read more
7 Catchy and Unique Business Name Ideas
Explore 7 catchy business name ideas that stand out! Get easy tips, hacks, and a splash of humor to kickstart your startup journey! Dive in and find your…
Read more